In this comprehensive Wealthsimple review, I will walk you through the platform’s features, pros, and cons.
This review is part of my series on the best Canadian crypto exchanges.
Overall Review 4/5
Wealthsimple is a large fund manager with $30 billion in assets under management and more than 3 million customers. It features two main products: a robo advisor that automatically invests your funds for those who want a more hands-off approach and self-directed investing for those who wish to be more involved and manage their own portfolio.
You can invest in Canadian stocks and ETFs as well as cryptocurrencies but not bonds and US securities. Depending on how much you deposit, there are different fees and perks. The platform assists you with tax-loss harvesting and offers a debit card that returns 1% cash back when you use it. Overall, Wealthsimple is a great solution for managing your crypto and traditional financial products in one place.
Pros and Cons

Pros
- Low fees on mutual funds
- Zero fees on self directed investments
- Cash card with 1% cash back
- 4% on high interest savings account
- Easy to use and automate your investments
- 60+ crypto coins

Cons
- 1.5% forex fees
- Fewer crypto coins compared to exchanges
- Lack of research tools for pro investors
- No bonds, no US-listed securities
- No joint account
- Only one savings account allowed
- No margin trading
Features
- Available as a mobile app on iOS and Android and as a website
- 1% bonus on deposits above $15,000
- 0% commissions on trades
- High-interest savings account at 4%
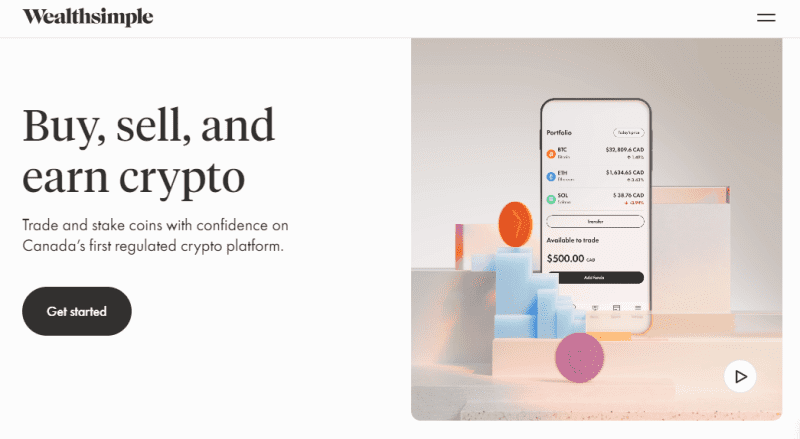
- Invest in stocks, ETFs, and 60+ cryptocurrencies
- Up to $500,000 on deposits is insured by the Canadian Investor Protection Fund
- Private equity investments for premium customers who deposit > $100K
- Security features such as two-factor authentication
- Tax filing software
- Cash card
Products
Wealthsimple offers two major product categories: managed investing and self-directed investing.
1. Managed investing
This is a mutual funds robo-advisor solution that automatically optimizes your investment portfolio.
You can choose to invest in three types of asset allocation:
- Classic, which invests in a diversified portfolio of ETFs
- Socially responsible for those who care about responsible investing
- Halal portfolio for those who wish to remain Shariah-compliant
For premium (>$100K) and Generation (>$500K) clients, there are also options to invest in:
- Private equity, where you invest in privately held companies for as little as $10K
- Private credit, where you earn 9% by lending your funds.
2. Self-directed investing
With self-directed investing, you can speak to human advisors and construct your portfolio however you want.
Individual investors can choose to invest in the stock market, exchange-traded funds and crypto as they please.
Novice investors can even buy individual stocks or fractional shares if they want to.
Savings account types with tax benefits
Wealthsimple offers four different types of savings accounts:
- Registered retirement savings plan (RRSP) whereby you can save up to $31K per year in a tax-deferred account
- Tax-free savings account (TFSA) whereby you can invest up to $95K without any tax penalties
- Locked-in retirement account ( where your investment can grow tax-free)
- First home savings account (FHSA): a tax-free way to save for a downpayment on a house.
Tiers and fees
<$100K
For clients depositing less than $100K, management fees are 0.5%.
$100K-$500K
Wealthsimple offers clients who deposit more than $100K a 0.4% management fee on managed investing accounts and 4.5% interest on cash accounts.
>500K
If you deposit more than $500,000, management fees drop to 0.2-0.4%, and you earn 5% on your cash deposits.
Pros
1. Low or no fees
Wealthsimple does not charge any fees for self-directed accounts.
E-transfers, direct deposits from your bank account, and bill payments are also free.
With respect to managed investing, while other mutual funds in Canada charge closer to 2%, Wealthsimple charges 0.2%-0.5%.
They even reimburse your transfer fees when moving cash about.
2. Cash card
By using the card, you earn 1% in cash back. The card has 0-dollar fees on forex transactions, whilst competitors usually charge 1.5-2.5%.
3. High-interest savings account
At the time of writing, you can earn 4% on your savings account, which is the highest I have come across in Canada.
4. Easy to use
They used to have a separate app for each of their business segments but have since consolidated everything into one app.
The Wealthsimple app and website are intuitive to navigate and use, and most customers are happy woth the user experience.
5. Automation
It is easy to automate deposits and investments, and you can automatically reinvest dividends.
6. Range of Cryptocurrencies
Wealthsimple Crypto offers more than 60 digital assets to choose from. For a platform that offers both stocks and ETFs, this is on the higher side.
The platform also allows you to send and receive crypto directly into your Wealthsimple account.
Check out my review of the best platforms to buy Bitcoin in Canada for more.
Cons
1. Forex fees
For those who frequently convert between USD and Canadian Dollars, the forex fee is on the higher side at 1.5%, and there is no Norbert’s Gambit.
2. Crypto support
i). A limited number of cryptocurrencies
If you are hoping to invest in coins with a low market cap, you won’t find them on Wealthsimple. You will need to choose a dedicated crypto exchange that is licensed in Canada, such as Coinbase, Kraken, or Crypto.com. These platforms offer more than 240 coins to choose from
ii). Custodial
Keep in mind that the crypto is not insured and that it is a custodial wallet, meaning you don’t have access to it if the company becomes insolvent.
iii). KYC
As a regulated company, you will need to verify your ID.
3. Lack of research tools
Wealthsimple is only five years old, and while it is expanding fast, its platform is missing certain features.
There are no research tools, analysis, or detailed financial statements.
Understanding how your portfolio has performed beyond the basics is very hard.
As it stands today, the interface is not appropriate for those who want a more hands-on approach to measuring the performance of their investments.
4. Range of financial products
Unfortunately, you can only invest in stocks and ETFs, but there is no option to invest in bonds or US-listed securities.
Lack of joint non-registered and spousal RRSP Wealthsimple Trade accounts.
No joint cash accounts.
5. User experience
Some customers complain of slow development and lack of coherence between web and mobile apps. Note also that there is no iPad app.
6. No option to set up multiple high-interest savings accounts
In addition, you can only create one high-interest savings account.
This means that you can’t set up different vaults for separate uses like you can with competing products.
7. Lack of features
- You can’t round up to the nearest dollar and put it away in savings
- You cannot trade on leverage.
- There is currently no option to set up a joint account with your spouse.
FAQs
Is Wealthsimple legit?
Wealthsimple is licensed in Canada and a Member of the investment industry regulatory organization of Canada
Is Wealthsimple good for beginners?
Wealthsimple makes life easy for new investors. The key to investing is to start early, and Wealthsimple uses modern portfolio theory to allocate funds.
Can I use Wealthsimple outside of Canada?
Wealthsimple is only available to Canadian residents. Unfortunately, you cannot use Wealthsimple in the United States.
Is there a monthly fee for Wealthsimple?
Fees are calculated on a daily basis and charged monthly to your account.
Can you make money using Wealthsimple?
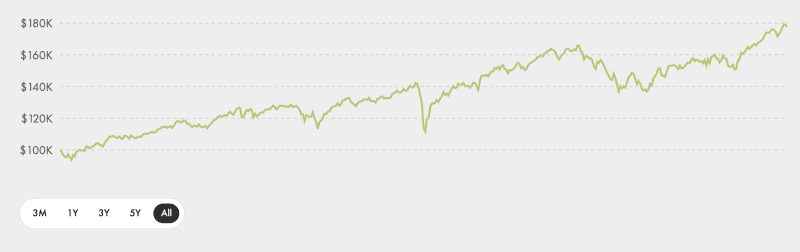
If you had invested $100K into Wealthsimple in 2016, this would now be worth $180K. So yes, by investing your funds according to a set plan, you can expect your long-term wealth to grow.
If you want to avoid fees altogether, you can use the self-directed option, but this means you should have some knowledge of how to structure a portfolio and what your investment goals are.
You can find data on Wealthsimple’s historical performance here.
Is Wealthsimple really free?
Wealthsimple offers zero commission fees on self-directed investments. Management fees for their robo-advisor service range from 0.2% to 0.5%, depending on how much you deposit with them.
Is Wealthsimple good for long-term investing?
Yes, Wealthsimple is considered the best robo-advisor platform by many of its customers. Any platform that facilitates investing on a recurring basis will allow you to grow your wealth over a long-term time horizon.
Can I invest $100 in Wealthsimple?
Yes, you can invest as little as $1 with Wealthsimple to start with.